Building Your Dream: A Developer’s Roadmap to Successful Construction Financing
Embarking on a new construction project is an exciting and often overwhelming venture. Whether building a single-family home or a commercial development, securing the right construction loans is essential to success. This guide will walk you through the entire financing journey—planning, applying, funding, and completing your project—while offering expert advice and best practices.
Step 1: Understanding Construction Loans
Before diving in, it's essential to know what construction loans are. These are short-term, high-interest loans used to finance the building of a property, released in stages as construction progresses. Unlike traditional mortgage loans, new construction loans cover the cost of construction before the property is completed and ready for sale or occupancy.
Step 2: Planning Your Project
A solid plan sets the foundation for a successful project. This involves:
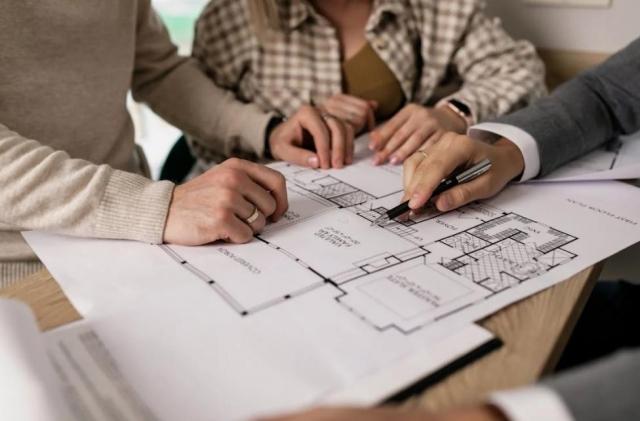
- Designing Your Project:Work with an architect to create blueprints that meet your vision.
- Budgeting and Estimating Costs:Break down every expense—land, materials, labor, and permits. A detailed budget is crucial to securing loans for construction.
- Choosing a Builder:Select a reputable contractor with a solid track record to avoid surprises.
Planning is key. The better your plans, the easier it will be to secure financing, as lenders want to see a clear vision and realistic cost estimates.
Step 3: The Loan Application Process
When applying for a construction loan, be ready with the necessary documentation:
- Tax returns, bank statements, and proof of income.
- Detailed project plans and cost estimates.
- Good credit historyand project feasibility.
Step 4: Securing Your Financing
Once approved, finalize your loan by reviewing these key factors:
- Loan Amount:Typically based on the project's estimated cost and sometimes factoring in the land's value. However, this can vary with different state-specific loans.
- Interest Rates:Higher than standard mortgages due to the loan's short-term nature. However, these rates can fluctuate based on location and project type.
- Repayment Terms:Understand the payment schedule, how interest will be calculated during construction, and the loan's conversion terms after the project is finished.
Securing the right loan is vital, as it directly impacts the overall success of the project.
Step 5: Managing the Construction Process
After securing funds, the next step is managing construction. The lender will release funds in stages once certain milestones are met, like the foundation or framing completion. Keep these in mind:
- Stick to the Schedule:Delays can affect financing and costs.
- Communicate with Your Lender:Notify your lender of any significant changes to the project. If delays happen or changes are made to the scope, the lender should be kept informed.
- Stay Within Budget:Avoid cost overruns by managing expenses carefully. It's critical to keep track of spending and ensure all unforeseen expenses are covered.
Make sure to keep detailed records of every milestone, as they'll help facilitate the disbursement of funds.
Step 6: Completing the Project and Loan Conversion
Once construction finishes, the loan usually converts into a long-term mortgage. This construction-to-permanent loan typically has lower interest rates and more favorable terms, which is ideal for developers looking to secure the property long-term. At this stage, the project is considered complete, and the transition to permanent financing is seamless.
Best Practices and Expert Advice
- Work with a Professional Team:Hire architects, contractors, and financial advisors to avoid pitfalls. A professional team can save you time, money, and frustration.
- Build in Contingencies:Always have a budget cushion for unexpected costs. Unforeseen circumstances, from weather delays to material price hikes, are common.
- Review Loan Terms:Ensure you understand every detail—interest rates, penalties, and repayment terms. Don't hesitate to negotiate for better terms if necessary.
Start Building Your Dream with the Right Financing Partner
Building your dream project takes careful planning and strategic financing. Whether you're considering construction loans in Baton Rouge, Boston, or Cleveland, Insula Capital Group can guide you through the process. Their team specializes in helping developers secure the right financing solutions for projects of all sizes. Learn more about their services and get started on your journey today at Insula Capital Group.
About the Author
The author is an experienced construction finance expert, helping developers and builders secure financing solutions for projects across the U.S. They specialize in guiding clients through the world of construction loans to ensure their projects are funded smoothly and efficiently.